Canadian business news — the Bank of Canada held its overnight rate at 2.25% on September 2, 2026, the seventh straight hold, and the message for borrowers is blunt: don’t expect relief soon. Headline inflation is stuck near 3% on the back of high gas prices, US tariffs keep escalating, and the bank is now openly warning the next move could be up, not down.
By Maplestime Business Desk | Ottawa, Ontario | September 19, 2026
Sources: Bank of Canada, Nesto, Money.ca | Last updated: September 19, 2026
Key Takeaways
- The Bank held the overnight rate at 2.25% on September 2, 2026 — the seventh consecutive hold, unchanged since the October 2025 cut from 2.50%
- Q2 2026 GDP grew 3.3% and unemployment fell to 6.4% in July, but the Bank says labour demand is still weak
- Headline CPI is hovering near 3% almost entirely because of gasoline; strip gas out and inflation is 2.2%
- New US tariffs on Canadian goods and the Middle East oil shock are the two risks the Bank is watching
- Next decisions: October 28 (with fresh projections) and December 9, 2026
The Seventh Hold in a Row
This is not a bank in a hurry. The September 2 decision keeps the overnight rate at 2.25%, the Bank Rate at 2.5%, and the deposit rate at 2.20% — all exactly where they’ve been since the last cut on October 29, 2025.
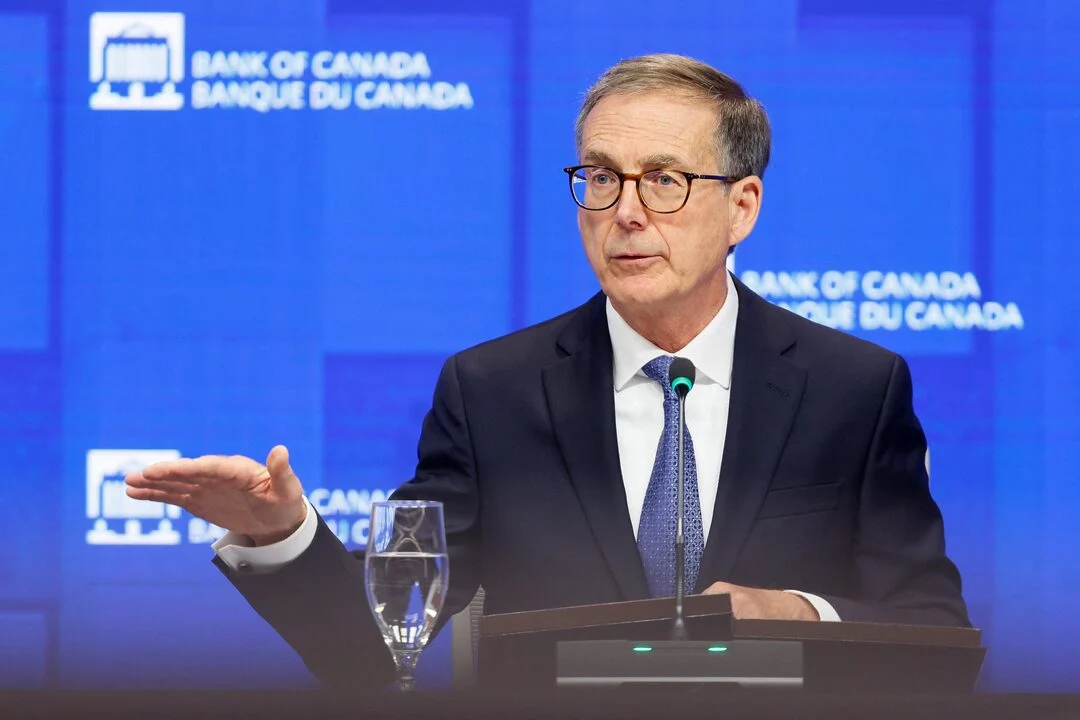
September wasn’t a Monetary Policy Report meeting, so Governor Tiff Macklem and Senior Deputy Governor Carolyn Rogers faced questions without a fresh set of projections. The next full forecast arrives October 28. Until then, the Bank’s message is steady: the economy and inflation have evolved broadly as forecast, so the rate stays put.
Why the Bank Won’t Cut Yet
Two forces are pulling the Governing Council in opposite directions — and neither is letting go.
The economy is healing. Second-quarter GDP grew 3.3% after a slow start to the year. Consumer spending is up, housing activity is rebounding, and exports and business investment rose sharply. The Bank calls it a broad recovery.
But inflation won’t behave. CPI has hovered around 3% for months — the very top of the Bank’s 1% to 3% target range. The twist: almost the entire overshoot is gasoline. Strip gas out and July inflation was 2.2%, with the Bank’s preferred core measures sitting near 2% (CPI-trim at 1.9%, CPI-median at 2%).
The Bank says it will look through an energy shock as long as it stays contained. So far, there’s little evidence of higher energy costs bleeding into other prices. The worry is duration: the longer businesses pay more for transport and production, the more likely those costs land on consumers.
What the September 2026 Hold Means for Your Mortgage
For variable-rate borrowers, nothing changes — prime stays at 4.45%, and payments hold where they are. Variable rates around 3.45% remain meaningfully cheaper than five-year fixed rates around 4.39%, a gap that’s been pricing in tariff and inflation risk through bond markets all year.
The pain is on renewals. Canadians who took mortgages at 1.5% to 2.5% in 2020 and 2021 are renewing at 4% to 5%, and homeowners who recently renewed are absorbing an average of $375 more per month, according to the Canada Mortgage and Housing Corporation. The September hold means no relief from that shock — and the Bank signalled it isn’t in a hurry to bring rates down further.
Savers, meanwhile, are still living in the best rate environment since 2020. High-interest savings accounts are paying 2.5% to 4.0%, and GICs are running 3.5% to 4.5%.
Related: High Interest Savings Accounts Canada 2026 — Where Your Money Actually Earns
Related: Canada Housing Crisis 2026: What’s Driving Prices and What Comes Next
Tariffs, Oil, and the Two Risks That Matter
Macklem’s press conference came with a warning aimed squarely at both sides of the border: “The added uncertainty about the future of Canada-US trade relations may lead businesses more broadly to delay investment and hiring decisions.”
The United States implemented another round of 50% levies against Canadian goods in September 2026, and Canada answered with dollar-for-dollar counter-tariffs. Add in the Middle East conflict — shipments through the Strait of Hormuz remain curtailed, keeping global oil prices high — and the Bank sees upside risks to its inflation forecast growing.
Monetary policy can’t fix either problem. Interest rates don’t reopen shipping lanes or settle trade wars. The Bank can only make sure those global shocks don’t permanently damage price stability in Canada.
What Comes Next
The Governing Council gave no forward guidance beyond a readiness to adjust as needed. What we know: the October 28 decision comes with fresh projections, and three data points will decide the next move — whether headline CPI stays parked near 3%, whether the Q2 growth rebound holds through the fall, and whether the tariff fight escalates or cools.
For now, plan around 2.25%. Stable, but expensive for borrowers and generous for savers.
Maplestime will provide updates from the Bank of Canada’s rate decisions as announcements are made.
Have a tip about the Bank of Canada rate decision? Email [email protected]
Have a correction? Email [email protected]
Is the Bank of Canada being prudent by holding at 2.25% — or is it asleep at the wheel while tariffs and gas prices squeeze Canadian households? Tell us in the comments. And share this with every Canadian who has a mortgage renewing this fall.
Enjoying Maplestime? Support independent Canadian journalism — no paywall, no corporate owners.