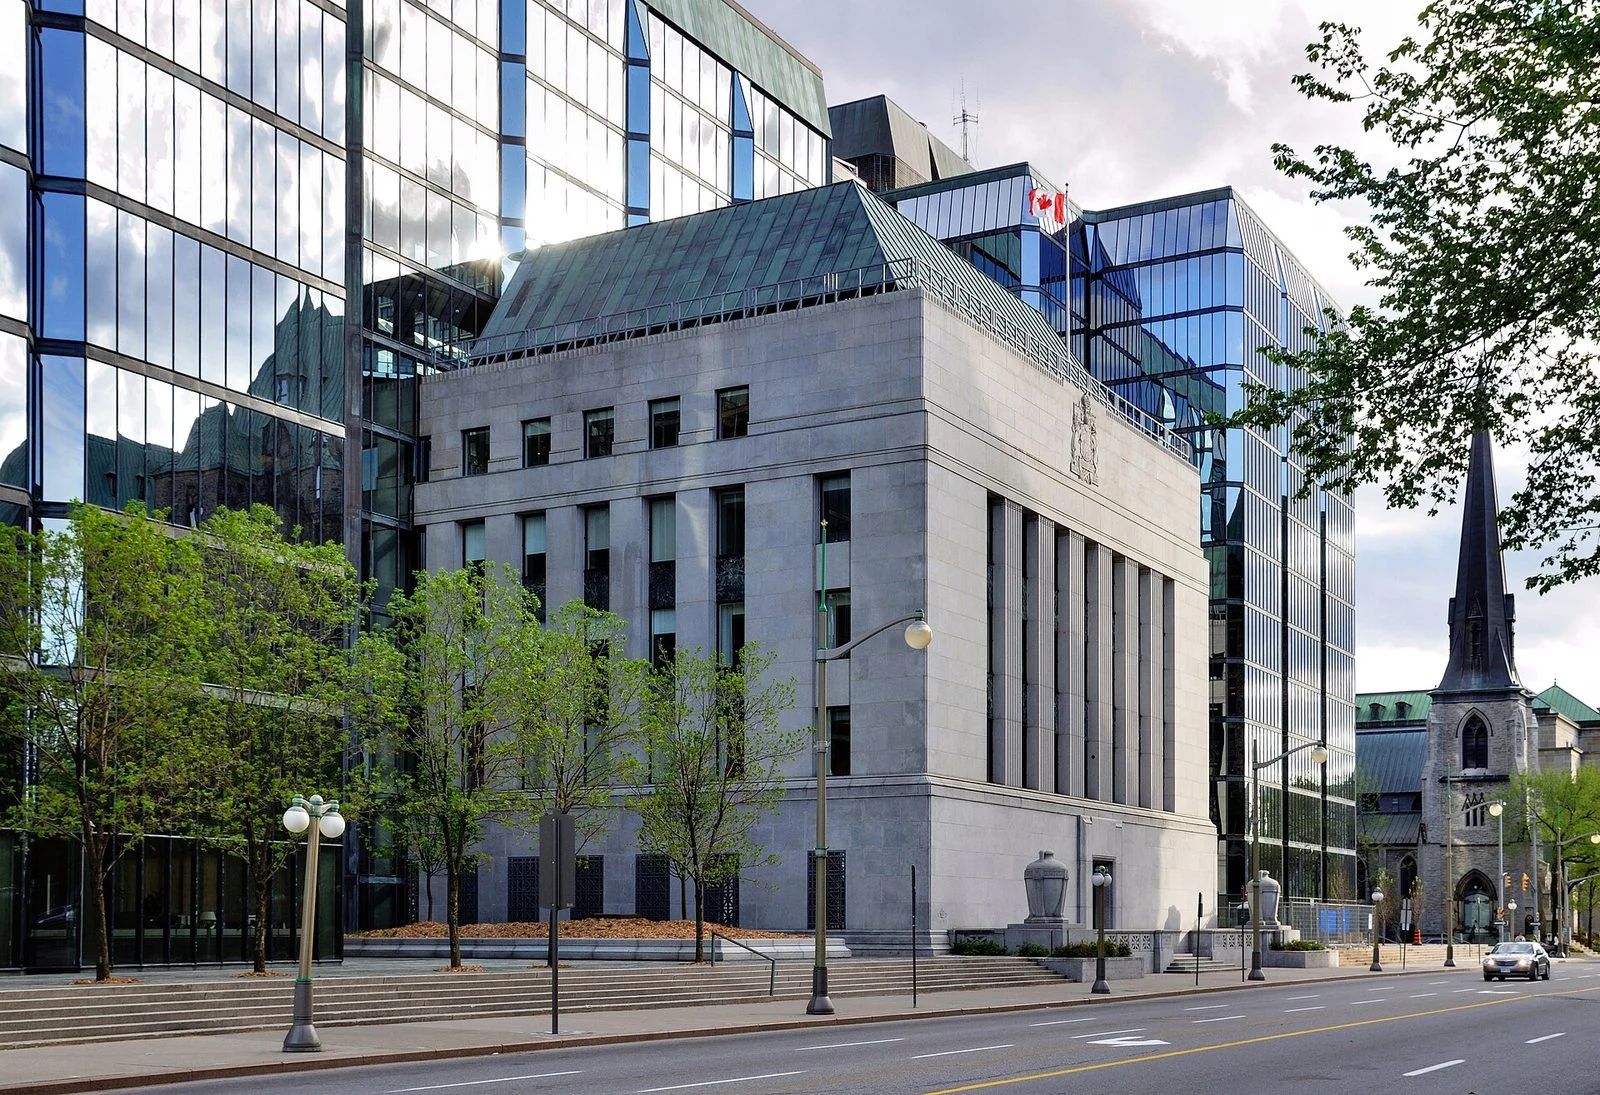
Canadian business news — the Bank of Canada December rate decision on December 9 has turned into the most argued-over call of the year, with traders and economists reading the same inflation numbers and reaching opposite conclusions.
By Maplestime Business Desk | Ottawa, Ontario | November 19, 2026
Sources: Canadian Mortgage Trends, Europe Says, e2gold, WatchTower Terminal, RateProbability | Last updated: November 19, 2026
Quick Answer: The Bank of Canada December rate decision comes December 9, with the policy rate at 2.50% after October’s hike. Pricing moved fast: Monday November 16 swaps priced a hold at 63.5%, while Thursday November 19 futures put a hike near 65%. October inflation held at 3.1%, below the Bank’s forecast, and economists are divided on what happens next.
Key Takeaways:
- The Bank of Canada next sets its policy rate on December 9, 2026, with the rate at 2.50% after a 25-basis-point hike in late October, the first increase since July 2023.
- October inflation held at 3.1% year over year, below the Bank’s 3.4% fourth-quarter forecast and the 3.2% Bloomberg consensus.
- Market pricing moved sharply during the week: Monday November 16 afternoon swaps implied a 63.5% chance of a hold, while Thursday November 19 futures pricing put a 25-basis-point hike at about 65%.
- Deputy Governor Toni Gravelle said November 18 that the Bank’s April scenario, which foresaw oil staying high and inflation near 3% for more than a year, had largely come true.
- Oxford Economics still expects a December hike, while CIBC’s Andrew Grantham expects the Bank to hold, and TD’s Leslie Preston called the October inflation signs lukewarm.
What Did Toni Gravelle Actually Say in Edmonton?
Deputy Governor Toni Gravelle spoke in Edmonton on November 18, and his message was blunt: the Bank saw this coming. In its April monetary policy report, the Bank sketched a scenario in which oil prices stayed elevated for months as the war in the Middle East escalated. It was not the base case, but in that scenario inflation would stay close to 3% for more than a year, which would require consecutive rate increases to bring it back to the 2% target.
By October, Gravelle said, that upside risk to inflation had largely materialized. The war had not ended, oil was still near 100 dollars a barrel, and refinery margins were running above historical norms, adding pressure to fuel prices. New American tariffs were adding to the uncertainty, but the economy was doing better than the Bank had expected. The October hike to 2.50% followed directly from that picture.
Gravelle also explained why the Bank now publishes scenario analysis more often. The aim, he said, is to shape rate expectations so market participants can interpret new information much like the Bank does and anticipate how policy might react. Economists call that the reaction function. He defended the decision not to publish a specific policy path, arguing that doing so leads markets to stop doing their homework and simply mirror what the central bank signals.
Why Is the Market Split on December 9?
Here is the honest answer: the market cannot agree with itself. Overnight swaps on Monday afternoon implied a 63.5% chance that the Bank holds its rate on December 9, according to market pricing reported this week. Futures pricing from WatchTower Terminal, cited on November 19, put a 25-basis-point hike at about 65%, and RateProbability’s overnight index swap model put it at 64.4%. And Bloomberg, reporting on Gravelle’s speech on November 18, put overnight-swap hike odds at about 60%.
Those numbers do not form one consistent picture, and they should not be read as one. They come from different measures taken at different moments in a fast-moving week, and the pricing has swung as each new piece of data lands. What they agree on is that December 9 is a genuine coin toss, not a foregone conclusion.
The economists are split the same way. Oxford Economics still expects the Bank to hike in December, arguing that inflation near 3% leaves the Bank with work to do. CIBC’s Andrew Grantham expects a hold, arguing that the October inflation print gives the Bank room to wait, and TD’s Leslie Preston called the inflation signs lukewarm. Both sides are reading the same report. They just disagree on what it means.
Related: Canada inflation holds at 3.1% as gas prices surge 30.9%
What Does the October Inflation Report Show?
Statistics Canada reported on November 16 that consumer prices rose 3.1% year over year in October, unchanged from September. That was below the Bank’s own 3.4% forecast for the fourth quarter and below the 3.2% Bloomberg consensus, which is why some economists think the pressure to hike has eased.
The core measures tell a softer story than the headline. CPI-median came in at 2.0%, CPI-trim at 1.8%, and CPI-common at 2.5%. Inflation excluding energy eased to 2.0% from 2.1% in September. The headline rate is being held up by energy prices, while the underlying trend looks closer to target than it did a few months ago.
That split is exactly why December 9 is so hard to call. The headline says inflation is stuck above target. The core says the Bank’s medicine is working. Gravelle’s speech suggests the Bank’s governing council is watching the same tension, and it has told markets plainly that decisions will be taken one meeting at a time.
What Will the Bank of Canada December rate decision Mean for Borrowers?
For anyone with a variable-rate mortgage or a renewal coming up, December 9 is the date that matters. A hold at 2.50% would mean borrowing costs stay where they are after the October increase, giving households a breather heading into the new year. Another 25-basis-point hike would push variable rates higher again and add to monthly payments for borrowers who are already stretched.
Savers face the mirror image. Higher rates have been good news for savings accounts and guaranteed investment certificates, and a hold would keep those returns roughly where they are. The October hike was the first increase since July 2023, a reminder that the long era of rate cuts is over and the Bank is now worried about inflation running hot, not about an economy running cold.
The practical advice is boring but correct: do not bet the household budget on one outcome. The market has swung from hold to hike and back inside a single week, and the economists paid to forecast this stuff are openly divided. If your renewal lands in December, talk to your lender now about what a hike would do to your payment, and what a hold would save you.
Frequently Asked Questions
When is the Bank of Canada’s next rate decision?
December 9, 2026. The policy rate currently stands at 2.50% after the Bank raised it by 25 basis points in late October.
Why are markets split on whether the Bank will hike or hold?
October inflation held at 3.1%, below the Bank’s forecast, which supports a hold. But energy prices and the Bank’s own scenario analysis point to inflation staying near 3%, which supports a hike. Different market measures taken on different days have pointed in opposite directions.
What did Deputy Governor Toni Gravelle say on November 18?
Speaking in Edmonton, Gravelle said the Bank’s April scenario, in which oil stayed elevated and inflation held near 3% for more than a year, had largely materialized. He said the Bank now publishes scenarios more often so markets can better anticipate how it will react to new data.
Maplestime will provide updates from the Bank of Canada’s December rate decision as announcements are made.
Have a tip about the Bank of Canada’s December rate decision? Email [email protected]
Have a correction? Email [email protected]
Do you think the Bank should hike again in December, or is holding at 2.50% the smarter call? Tell us in the comments. And share this with every Canadian watching a mortgage renewal and the cost of living this week.
Enjoying Maplestime? Support independent Canadian journalism — no paywall, no corporate owners.